Does Homeowners Insurance Cover Storm-Damaged Siding in NC
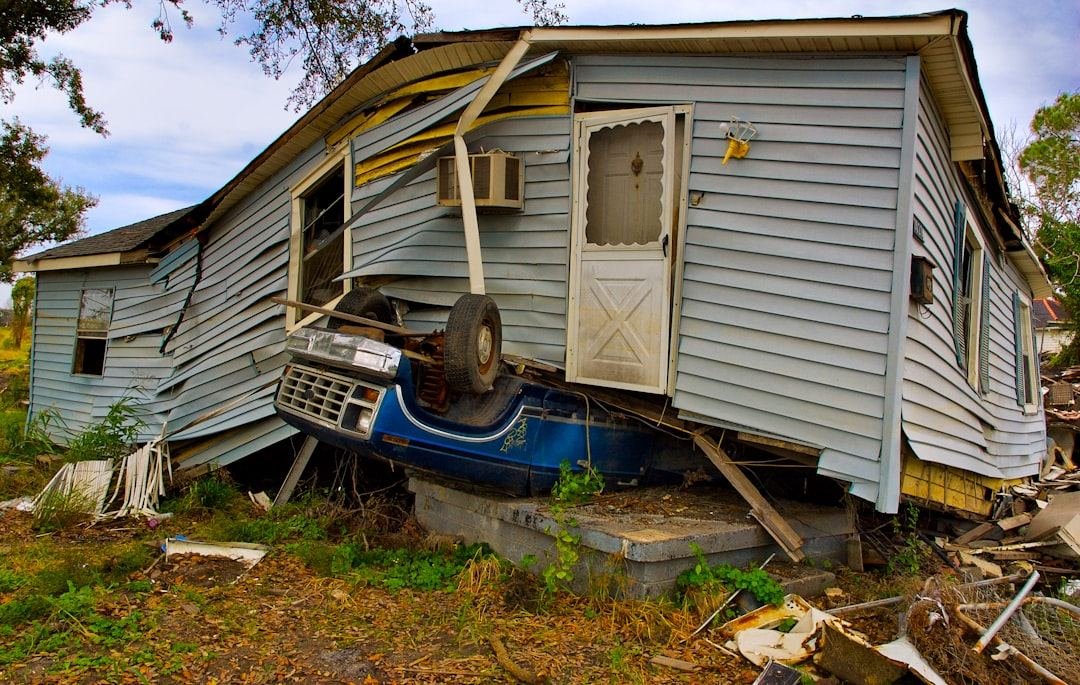
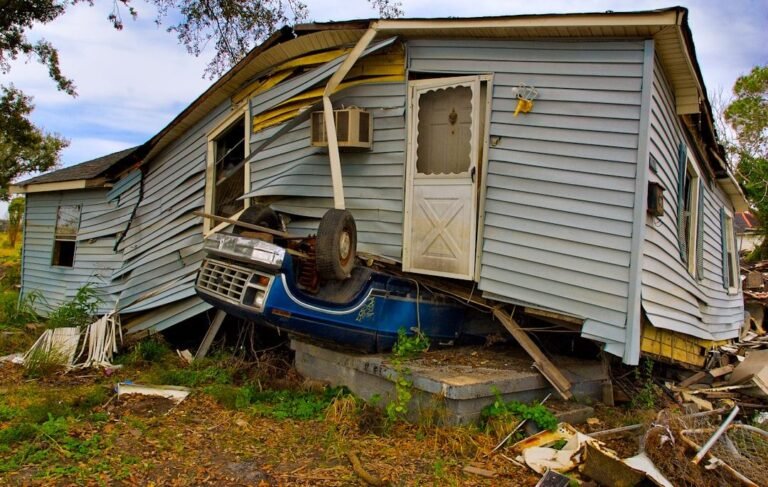
North Carolina homeowners insurance typically covers siding damage caused by wind, hail, or falling debris from a storm, but coverage depends heavily on how clearly the damage can be tied to a specific storm event versus attributed to gradual wear the policy likely excludes — documentation quality often matters as much as the damage itself in how a claim gets resolved.
See siding repair services if you’re dealing with recent storm damage. For general guidance on filing a homeowners claim in NC, the NC Department of Insurance publishes a consumer’s guide to the claims process worth reading before your first call to your carrier.
Photo by John Middelkoop on Unsplash
Why “Storm Damage” and “Wear and Damage” Get Confused
Insurance policies generally distinguish between sudden, identifiable events (a specific storm cracking a panel) and gradual deterioration (siding that’s simply aged out or was already compromised before the storm). An adjuster’s job includes determining which category applies, and pre-existing wear — faded, brittle, or already-cracked siding — can complicate a claim even when a real storm did cause additional damage, since it becomes harder to separate what the storm caused from what was already there.
What Typically Isn’t Covered
Damage from long-term neglect (siding that was never repaired despite years of visible problems), damage from a source unrelated to a covered peril (settling, general aging), and damage below your policy’s deductible are the most common reasons a claim gets denied or only partially covered, separate from any dispute about whether a storm occurred at all.
| Claim Component | Typically Covered | Typically Not Covered |
|---|---|---|
| Wind-driven panel damage from a specific storm | Yes | — |
| Hail impact damage | Yes | — |
| Damage attributed to years of unaddressed wear | — | Usually not |
| Damage below policy deductible | — | Out of pocket |
Working With a Public Adjuster vs. Going Directly Through Your Insurer
For larger, more disputed claims, some homeowners hire an independent public adjuster who represents the homeowner’s interests rather than the insurance company’s, typically for a percentage of the settled claim amount. This isn’t necessary for straightforward, clearly documented storm damage, but it’s worth knowing as an option if your insurer’s initial assessment seems to significantly understate the damage compared to your own contractor’s estimate and the disagreement isn’t resolving through normal channels.
Getting a Fair Assessment
Getting your own contractor’s written estimate before or alongside the adjuster’s visit gives you a documented, independent comparison point if the insurance company’s assessment seems to understate the actual repair scope.
Documentation That Actually Helps Your Claim
- Photos taken as soon as possible after the storm, before any temporary repairs, showing the damage in context (wide shots of the affected wall, not just close-ups of individual panels).
- A record of the specific storm date, which can be cross-referenced against local weather data if the claim is disputed.
- Photos of the same area from before the storm, if you have any (previous listing photos, old renovation photos, even casual photos that happen to show the wall) — this helps establish the damage wasn’t pre-existing.
- A written contractor estimate describing the damage and likely cause, obtained before or alongside the adjuster’s visit.
Warning: Filing a claim weeks or months after a storm, rather than promptly, can weaken your case — the longer the gap, the more room there is for an adjuster to question whether the damage is storm-related or developed afterward from ongoing exposure. File as soon as reasonably possible after discovering the damage.
DIY vs. Professional Contractor
| Situation | DIY Feasible | Call a Contractor |
|---|---|---|
| Photographing and documenting damage | Yes | N/A |
| Getting a written repair estimate | No | Yes, before or alongside adjuster visit |
| Actual repair work | No | Yes |
Common Questions
Does NC homeowners insurance cover storm-damaged siding?
Typically yes for wind, hail, or debris damage from a specific storm, but adjusters distinguish that from gradual wear the storm merely exposed. Photograph damage immediately, before any temporary repair.
Get your free siding quote
Matched with an independent, licensed local contractor
No cost, no obligation to move forward
Most quote requests get a response within 1-2 business days
By submitting this form you consent to be contacted by phone, text, or email regarding your project, including by automated means. Consent is not a condition of purchase. Message and data rates may apply. See our Privacy Policy and Terms of Use.
Wilson Exteriors Pro is an independent local information and referral service. We are not a licensed contractor and do not perform siding or window installation ourselves. Project requests submitted through this site may be shared with an independent, licensed local contractor for a free estimate.